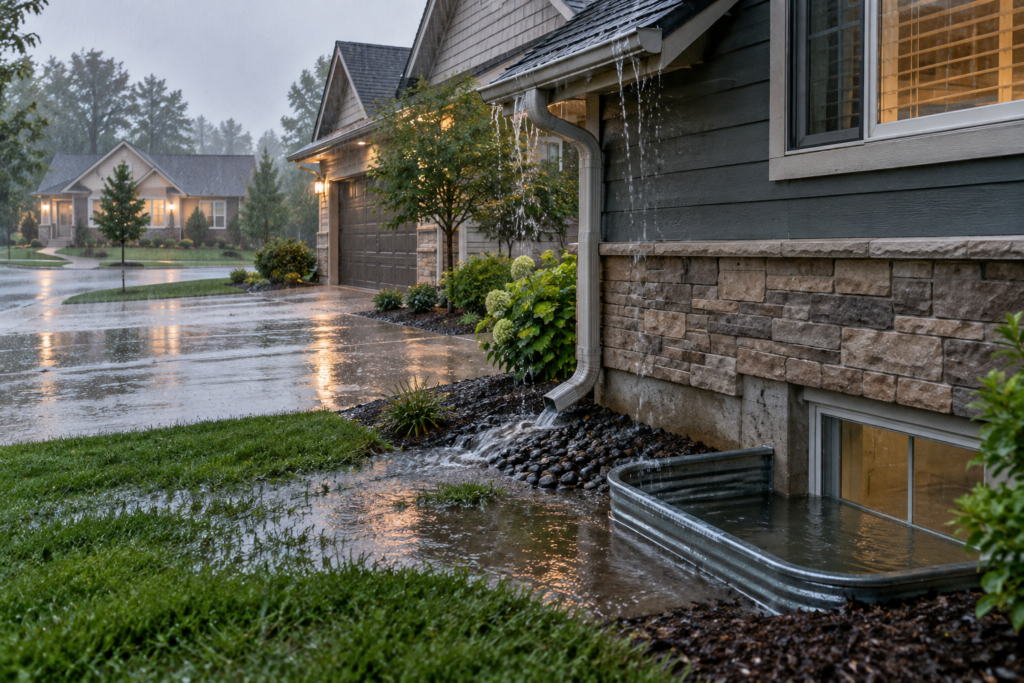
Water-related losses are some of the most misunderstood home insurance claims. Homeowners often assume that anything involving water, a sewer, or an underground pipe is covered the same way. In reality, water backup, buried service line damage, and flooding are separate exposures that may require different coverage.
Water backup coverage protects against water coming back into the home
Water backup coverage generally applies when water or sewage backs up through a drain, sewer, sump, or similar system and damages the inside of your home or your belongings.
This coverage is commonly added by endorsement and usually has its own limit. Without it, a standard homeowners policy may provide little or no protection for this type of loss.
Buried service line coverage protects the underground lines serving your home
Buried service line coverage is different from water backup. It is designed to help pay for damage to certain underground utility or service lines that you are responsible for, such as water, sewer, electrical, or other covered lines running between your home and the public connection.
This type of coverage can help with excavation, repair, replacement, and related damage when a covered service line fails. Limits vary by carrier, and some companies cap this coverage at a relatively modest amount.
Flood coverage addresses water coming from outside the home
Flood insurance is a separate issue entirely. Standard homeowners insurance generally does not cover flood damage caused by rising surface water, storm surge, overflowing bodies of water, or similar flooding events.
A separate flood policy may be needed to protect the home and belongings against those losses. This can matter even outside traditional high-risk flood zones, because flooding can occur from heavy rain, drainage problems, and other events that are not covered by a standard homeowners policy.
Water backup, service line, and flood coverage are not interchangeable
- Water backup: Generally addresses water or sewage backing up through drains, sewers, sumps, or similar systems into the home, subject to the policy endorsement and limit.
- Buried service line: May help pay for covered damage to underground utility or service lines you are responsible for, including excavation and repair costs.
- Flood insurance: Generally addresses flooding from rising or overflowing surface water and usually requires a separate flood policy.
Why the distinction matters
A homeowner can have excellent homeowners insurance and still have gaps involving water. The important question is not simply whether you have “water coverage,” but which types of water losses your policies actually address and what limits apply.
Coverage availability, definitions, exclusions, and limits vary by insurance company, so these protections should be reviewed based on the specific policy rather than assumed from the coverage name alone.
Review the coverage before a loss happens
If you are unsure how your homeowners policy handles water backup, buried service lines, or flood exposure, reviewing those coverages before a claim can prevent an unpleasant surprise later.
Need help reviewing your homeowners coverage?