JERSEY SHORE COASTAL & SECOND HOME INSURANCE · NEW JERSEY

Jersey Shore home insurance built for coastal and second homes.
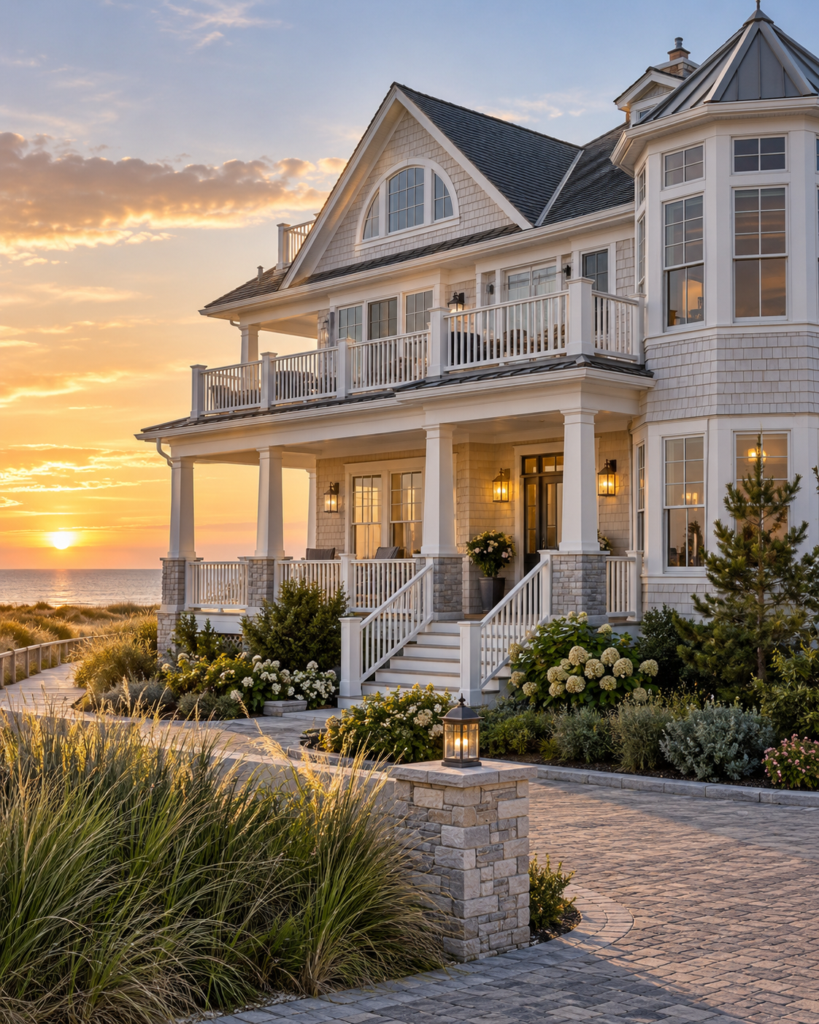
Shore homes bring different underwriting challenges than properties farther inland. From Avalon and Stone Harbor to Sea Isle City, Cape May, and the Wildwoods, wind exposure, flood risk, seasonal occupancy, rental use, and coastal construction can all affect the right insurance strategy.
Personal insurance hero image representing home, auto, umbrella, and household asset protection for Pennsylvania and New Jersey clients.
CORE JERSEY SHORE COVERAGE

The coast changes the risk — and the insurance.

COASTAL HOME INSURANCE

Protect the property itself.

Coverage for the dwelling, belongings, additional living expenses, and liability—structured around the home’s location, construction, occupancy, wind exposure, and coastal underwriting.
FLOOD INSURANCE

Flood is a separate exposure.

Standard homeowners insurance generally does not cover flood. I evaluate NFIP and private flood options separately based on the property’s flood zone, elevation, construction, value, occupancy, and overall coastal exposure.
SECOND HOME INSURANCE

A second home brings different questions.

Seasonal occupancy, time spent vacant, distance from your primary residence, property management, rental use, and storm exposure can all affect underwriting and the right coverage structure for a Jersey Shore home.
WHERE COASTAL RISKS GET COMPLICATED

The location changes more than the premium.

Jersey Shore properties can face wind, flood, elevated construction, seasonal occupancy, rental exposure, and underwriting restrictions that ordinary homeowners policies may never encounter. The details of the property, where it sits, and how it is used all matter.
Request a Coastal Insurance Review →

Wind and hurricane deductibles can change the equation.

Coastal policies may use separate wind or named-storm deductibles that are much higher than the standard homeowners deductible. Those terms matter when evaluating the real out-of-pocket exposure.

Elevation and construction affect underwriting.

Pilings, foundation type, roof age, distance from the water, building materials, and mitigation features can all influence carrier appetite, pricing, and available coverage.

Seasonal use changes the risk.

A second home that sits vacant for part of the year, is occasionally rented, or relies on a caretaker or property manager can need different coverage than a primary residence.
BUILT AROUND THE PROPERTY

Two Jersey Shore homes can look similar and still need very different insurance.

Location, elevation, construction, occupancy, flood exposure, rental use, and distance from the water can all change how a Jersey Shore coastal insurance program should be structured.
01

YOUR PROPERTY

Construction type, roof age, foundation, elevation, updates, replacement cost, and proximity to the water can all affect coastal underwriting, carrier appetite, and available coverage.
02

YOUR USE

Primary residence, second home, seasonal occupancy, short-term or seasonal rental use, property management, and periods of vacancy can create very different insurance needs.
03

YOUR EXPOSURE

Flood zones, wind and named-storm exposure, storm deductibles, water backup, property values, and liability around the home all need to be considered together.
Explore Flood Insurance →
WHY JOE

Coastal insurance takes more than finding a homeowners quote.

Shore properties can require different carriers, different underwriting information, and different coverage decisions than a typical primary home. The value is knowing what to ask, where the gaps can appear, and which markets actually fit the property.
INDEPENDENT COASTAL MARKET ACCESS · NEW JERSEY

More markets matter when the property is harder to place.

Coastal location, wind exposure, flood, seasonal occupancy, rental use, older construction, and second-home occupancy can narrow carrier appetite quickly. One of the coastal markets I frequently work with is Great Bay, along with other admitted and specialty markets when the property calls for a different approach.
COASTAL EXPERIENCE

The Jersey Shore is a different insurance market.

Jersey Shore homes often require more underwriting detail and a broader market approach than a typical primary residence. When standard coastal markets are not the right fit, specialty options—including Lloyd’s market placements when appropriate—may also be considered. The focus stays on matching the property, occupancy, flood exposure, liability, and coverage structure to the right market.
JERSEY SHORE INSURANCE FAQ

Common questions about insuring a Jersey Shore home.

Coastal and second homes can create insurance questions that do not come up with a typical primary residence. These are some of the issues I review most often with Jersey Shore property owners.
READY FOR A BETTER COASTAL INSURANCE CONVERSATION?

Let’s make sure your Jersey Shore property is protected for the risks that actually come with it.

Tell me about the property, where it is located, how you use it, whether it is rented, and what coverage you have now. I’ll help evaluate the home, flood exposure, wind and storm deductibles, liability, and available coastal insurance markets so you can make the right next move.
Joe Moore Insurance
Independent Insurance Advisor | Pennsylvania & New Jersey
joe@joemooreinsurance.com
© 2026 Joe Moore Insurance. All rights reserved.
Website strategy & design by MOORE DIFFERENT — Independent Marketing & Brand Consulting