HOA & CONDO ASSOCIATION INSURANCE · PENNSYLVANIA + NEW JERSEY

HOA & condo association insurance built around the property, board, and responsibilities behind the community.
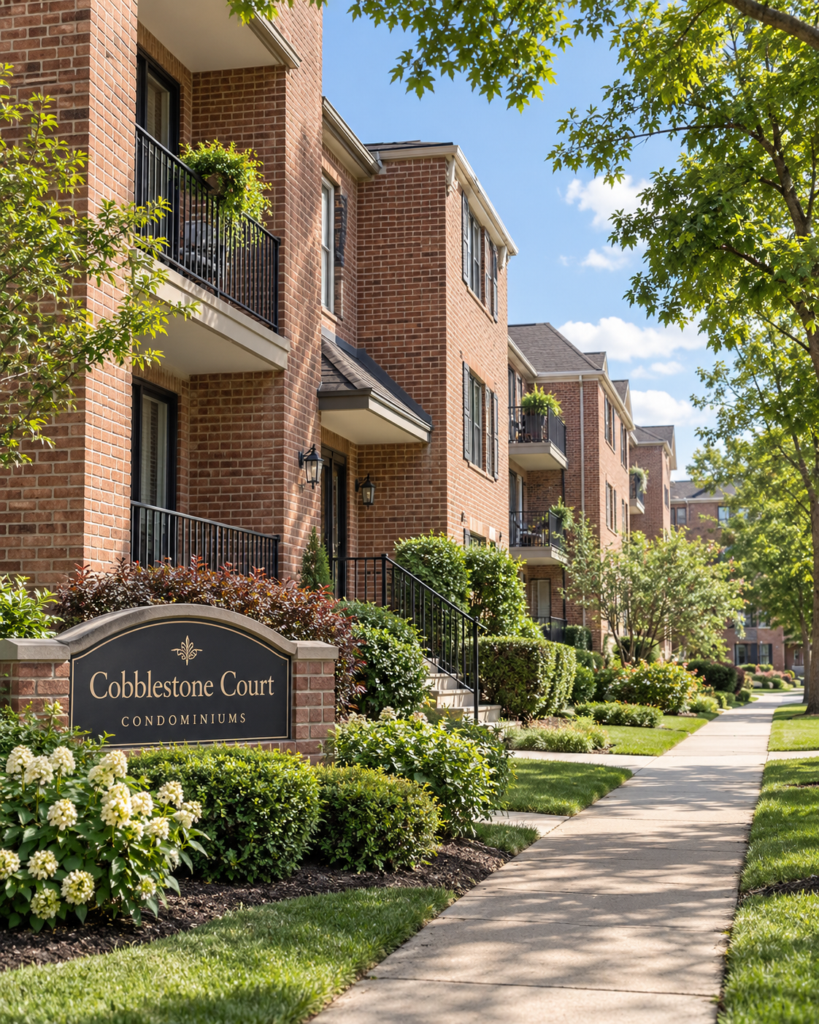
HOA and condo association insurance can involve very different responsibilities depending on the property, governing documents, building structure, common areas, amenities, contracts, and the board’s obligations. The master policy should reflect what the association is actually responsible for—not simply the number of units or buildings.
Business owner reviewing plans in a commercial operation with employees, vehicles, tools, and equipment
WHAT ASSOCIATION INSURANCE NEEDS TO ADDRESS

Start with the property, liability, and board exposures the association is responsible for.

MASTER PROPERTY

Protect the property the association is responsible for.

Coverage may include association-owned buildings, common elements, structures, fixtures, equipment, and other property defined by the governing documents. Replacement cost, ordinance or law requirements, deductibles, and responsibility for building components all need to be reviewed carefully.
GENERAL LIABILITY

Protect against claims arising from common areas and association operations.

Liability coverage can help address covered bodily injury and property-damage claims involving common areas, sidewalks, parking areas, pools, clubhouses, association activities, maintenance operations, and other premises exposures.
DIRECTORS & OFFICERS

Protect the people making decisions for the association.

Directors and officers liability can help protect the association and board members against certain claims involving governance, elections, assessments, covenant enforcement, management decisions, and other board responsibilities.
WHERE ASSOCIATION INSURANCE GETS COMPLICATED

The declarations page is only part of the answer. The governing documents matter too.

Two communities with the same number of units can need very different insurance programs. Building ownership, common elements, governing documents, maintenance responsibilities, amenities, replacement values, deductibles, contractors, and unit-owner responsibilities can all affect how the master policy should be structured.
Request an Association Insurance Review →

The master policy needs to match the association’s responsibility.

Condominium declarations, bylaws, plats, maintenance responsibilities, and other governing documents can help determine which buildings, common elements, fixtures, and other property the association is expected to insure. Whether the documents contemplate a bare-walls, single-entity, or all-in approach can materially change how the master property coverage should be structured.

Replacement cost needs to reflect the actual property.

Building construction, square footage, common elements, finishes, mechanical systems, local construction costs, ordinance or law requirements, and shared structures can all affect appropriate property limits.

Deductibles and unit-owner responsibility can create unexpected gaps.

Large property, wind, water, or named-storm deductibles can create significant financial exposure after a loss. The governing documents should also be reviewed to understand when the association’s responsibility ends, when the individual unit owner’s HO-6 coverage begins, and whether a deductible or portion of a loss may ultimately be assessed back to unit owners.
BUILT AROUND THE COMMUNITY

Two associations can look similar and still need very different insurance.

Property ownership, governing documents, common areas, amenities, replacement values, board responsibilities, contractors, and deductibles can all change what the right association insurance program looks like.
01

Condominium Master Policies

Building structure, common elements, association responsibility, unit-owner responsibility, replacement cost, deductibles, and governing documents all need to work together when structuring the master policy.
02

Homeowners Associations

Common property, private roads, landscaping, signs, fencing, clubhouses, recreational areas, and other association-owned assets can create a very different risk profile from a condominium.
03

Common Areas & Amenities

Pools, clubhouses, playgrounds, parking areas, walkways, elevators, gates, fitness facilities, and other shared amenities can increase both property and liability exposure.
04

Directors & Officers Liability

Board decisions, elections, enforcement, assessments, contracts, and governance disputes can create management-liability exposures.
05

Crime & Fidelity

Association funds, reserve accounts, employee or board access to money, vendor payments, and financial controls can create crime and fidelity exposures that should be reviewed carefully.
06

Flood, Equipment Breakdown & Excess Liability

Flood may require separate coverage, while boilers, mechanical systems, elevators, and other equipment can create equipment-breakdown exposures. Umbrella or excess liability, cyber coverage, ordinance or law, and other specialized protections should also be reviewed based on the association’s property, operations, contracts, and overall exposure.
Explore Commercial Property Insurance →
WHY JOE

You don’t need another master-policy quote. You need someone who understands what the association is actually responsible for.

Association insurance sits at the intersection of property, liability, governance, contracts, and community responsibilities. In addition to working with association insurance, I serve as an HOA treasurer myself, which gives me firsthand perspective on budgets, reserves, contracts, assessments, maintenance responsibilities, and the decisions boards have to make. The goal is to understand the property and governing structure first, then build the insurance around it.
INDEPENDENT ADVICE · PENNSYLVANIA + NEW JERSEY

More than one market. More than one way to protect the association.

I compare available association markets based on the buildings and common property, governing documents, replacement values, amenities, board responsibilities, loss history, contractual requirements, deductibles, and the coverage the community actually needs.
RECOGNIZED PERFORMANCE

Performance recognized. Recommendation still independent.

Nationwide recognized Joe as a Q1 2026 top performer across Southeastern Pennsylvania. But no single carrier drives the recommendation. The focus stays on finding the coverage and market that best fit the association and property behind it.
HOA & CONDO ASSOCIATION INSURANCE FAQ

Common questions boards should ask about the master policy.

Association insurance decisions can affect the buildings, common property, board members, finances, and individual unit owners. These are some of the issues I review most often with HOA and condominium associations.
READY FOR A BETTER ASSOCIATION INSURANCE CONVERSATION?

Let’s make sure the master policy reflects the property and responsibilities behind the community.

Tell me about the association, buildings, common areas, amenities, replacement values, governing documents, current deductibles, board coverage, loss history, and any lender or contractual requirements. I’ll help identify potential gaps, evaluate the structure of the master policy, and compare available association insurance markets.
Joe Moore Insurance
Independent Insurance Advisor | Pennsylvania & New Jersey
joe@joemooreinsurance.com
© 2026 Joe Moore Insurance. All rights reserved.
Website strategy & design by MOORE DIFFERENT — Independent Marketing & Brand Consulting